Uncovering Utility Misclassification Errors at a National Steel Company
How an independent, contingency-based audit conducted behind the company’s existing energy management contract uncovered utility-level misclassification errors across seven states, recovering $374,326 in refunds and identifying more than $150,000 in new annual recurring savings, with no changes to plant operations.
An Audit Gap an Existing Energy Contract Didn’t Close
A publicly traded national steel company, operating dozens of industrial and manufacturing facilities across the United States, was already under contract with an energy management provider for procurement and auditing services when Discovery Energy proposed an independent, contingency-based audit conducted behind that existing relationship.
Discovery Energy’s review, based on an initial sample of the company’s utility bills, found indications that several accounts were not receiving the scrutiny their scale warranted, despite an active audit relationship already in place. Discovery Energy proceeded on a contingency basis, auditing behind the completed work of the company’s existing provider.
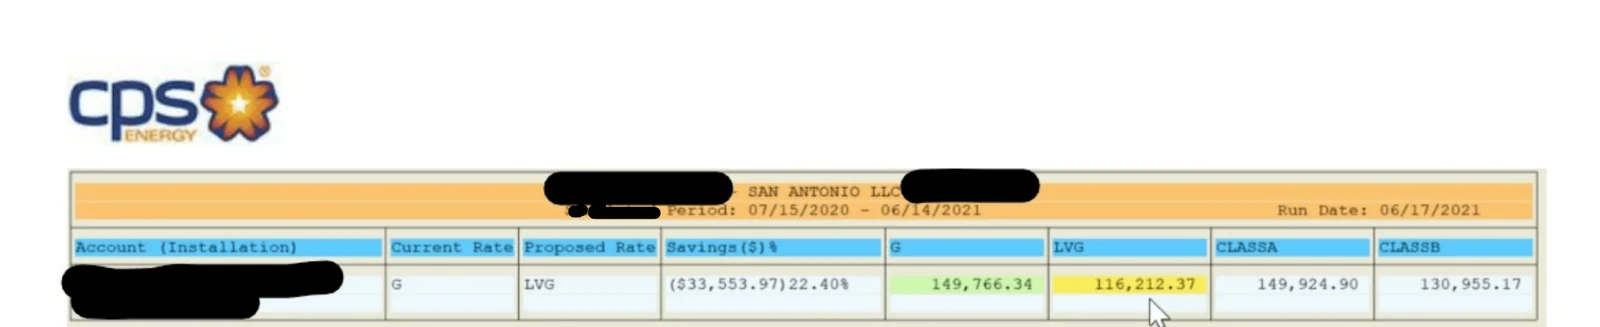
That audit identified that several of the company’s utility accounts had been misclassified at the utility level, assigned to the wrong rate class for their usage profile, across facilities in seven states. Discovery Energy also identified more than $150,000 in new annual recurring savings across the portfolio, including a single gas account reclassification worth $33,554 per year, documented in this case study as a verified example.
“Seventeen misclassified accounts, in seven states, sitting behind an active energy audit contract, found only once someone checked each account’s classification against the utility’s own criteria.”
This case illustrates a category of utility billing error that an existing audit or energy management relationship does not automatically catch: incorrect rate classification at the utility level. Verifying it requires testing each account’s assigned class directly against the utility’s own classification criteria, not simply reviewing invoices for competitive pricing or usage anomalies.
A Large, Multi-Site Portfolio, Still Exposed to Classification Risk
The company operates dozens of industrial and manufacturing facilities across the United States, with utility accounts spanning multiple states, utilities, and rate structures.
Portfolios of this scale generate utility billing complexity that even an active energy management relationship does not fully eliminate: procurement-focused audits are built to negotiate competitive supply contracts, not necessarily to verify that each individual account has been assigned the correct rate class by the utility itself.
Discovery Energy reviewed a sample of the company’s utility bills and identified indications that certain accounts were not receiving the scrutiny their scale warranted. On that basis, Discovery Energy proposed an independent, contingency-based audit, conducted behind the company’s existing energy management contract, rather than in place of it.
That existing contract is a meaningful data point in its own right. It confirms the company was not without oversight of its utility accounts, an active energy management relationship, covering procurement and auditing services, was already in place across its portfolio. That relationship did not surface the utility-level misclassification errors Discovery Energy later identified, which speaks less to any shortfall in that engagement than to the nature of the error itself: confirming that a utility has assigned the correct rate class to an account is a distinct, utility-specific check, separate from the competitive-pricing and supply-contract work most energy management engagements are scoped around.
Why This Was Hard to Catch Behind an Existing Audit
Rate misclassification doesn’t look wrong on an invoice. The bill is calculated correctly for the class it’s been assigned, the class itself is simply the wrong one for that facility’s usage profile. Catching it requires testing each account’s classification directly against the utility’s own criteria, account by account, which sits outside the scope of most procurement-focused energy management engagements.
Discovery Energy conducted its audit independently and on a contingency basis, behind the existing provider’s completed work.
Testing Utility-Assigned Rate Classifications, Account by Account
Discovery Energy’s audit methodology tests each utility account’s assigned rate class against the utility’s own classification criteria, independent of, and in addition to, any existing energy management review.
Reviewed an initial sample of the company’s utility bills
Identified early indications that certain accounts were not being scrutinized at the level the company’s scale warranted, despite an active energy management contract.
Proposed and conducted an independent, contingency-based audit
The audit ran behind the company’s existing provider, testing accounts already reviewed under that separate, procurement-focused engagement.
Tested each account’s utility-assigned rate class against its usage profile
This meant confirming classification criteria directly with each utility, rather than relying on the account’s billing history alone.
Identified misclassification errors across seventeen accounts in seven states
Errors were found at facilities in Indiana, Massachusetts, Nebraska, Minnesota, Colorado, Texas, and Missouri.
Separately identified a more favorable tariff classification
A San Antonio, Texas gas account qualified for reclassification from its current G rate schedule to the LVG rate schedule, producing new recurring savings.
Why It Matters Beyond This Portfolio
The fact that misclassification errors were found on seventeen separate accounts, across seven states and multiple utilities, indicates a pattern that a single-site or invoice-level review is unlikely to surface, but a systematic, account-by-account classification audit is built to find, especially across a portfolio this size.
$374,326 in Verified Refunds, Plus $150,000+ in New Recurring Savings
Recovered across 17 misclassified utility accounts in seven states.
Identified across the portfolio, including a documented $33,554 example.
Discovery Energy’s audit produced verified recovery across seventeen utility accounts in seven states, plus more than $150,000 in new annual recurring savings identified across the portfolio. One of those savings opportunities, a gas account reclassification in San Antonio, Texas, is documented below as a verified example:
| Facility (State) | Utility | Refund |
|---|---|---|
| Indiana | Muncie Gas & Electric | $34,347 |
| Indiana | Hamilton Gas | $60,383 |
| Massachusetts | Plymouth Gas | $28,504 |
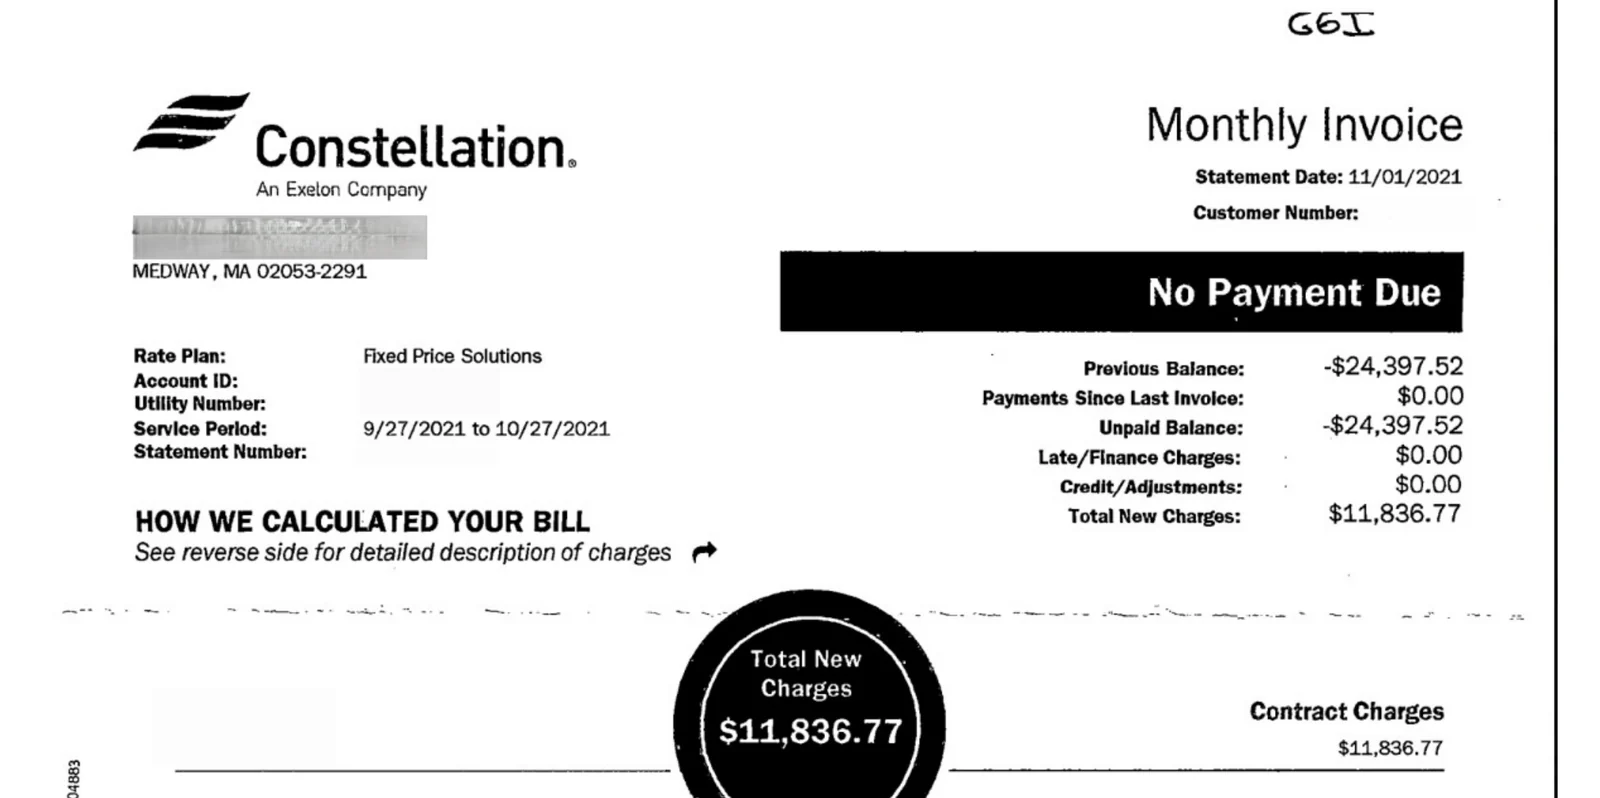
| Massachusetts | Constellation | $24,397 |
| Nebraska | Constellation | $11,175 |
| Nebraska | Constellation | $20,860 |
| Minnesota | Xcel Energy | $22,103 |
| Minnesota | Xcel Energy | $28,499 |
| Colorado | Xcel Energy | $7,232 |
| Colorado | Xcel Energy | $5,536 |
| Texas | CPS Energy | $19,919 |
| Texas | CPS Energy | $45,822 |
| Texas | Gas South | $7,658 |
| Texas | Infinite Energy | $12,818 |
| Texas | Luminant Energy | $20,568 |
| Missouri | Evergy | $13,248 |
| Missouri | Spire Energy | $11,257 |
| Total Verified Refunds | $374,326 | |
More than $150,000 in additional new annual recurring savings was identified across the portfolio. The $33,554 figure documented below reflects one verified account within that total, not the full portfolio-wide amount.
An Active Audit Relationship Doesn’t Guarantee Correct Classification
This engagement illustrates a specific failure mode in multi-site industrial utility portfolios: an account can be reviewed under an active energy management contract and still be misclassified at the utility level.
For a portfolio of this scale, seventeen separate misclassification errors across seven states produced a combined $374,326 in refunds, plus more than $150,000 in new annual recurring savings identified across the portfolio, including a single gas account reclassification worth $33,554 per year. Left uncorrected, each of these errors would have continued to compound with every billing cycle.
Procurement-focused energy management is well suited to negotiating competitive supply contracts and identifying usage anomalies. It is less well suited to verifying that a utility has assigned the correct rate class to a given account, because that verification requires testing each account directly against the utility’s own classification criteria, independent of pricing.
That is the specific gap Discovery Energy’s audit methodology is built to close: testing utility-assigned classifications directly, behind any existing audit or energy management relationship, rather than assuming an active contract has already covered it.
Questions This Raises for Multi-Site Portfolios
- Has every account’s rate class been verified directly against the utility’s own classification criteria, not just reviewed for competitive pricing?
- If one facility’s account was misclassified, have sibling facilities on the same utility been checked?
- Does the current energy management or audit scope include utility-side classification verification, or only supply-side procurement?
What This Recovery Demonstrates
- An active audit relationship is not the same test as a classification audit. The company’s existing energy management contract covered procurement and auditing services, but the utility-level misclassification errors surfaced only once Discovery Energy tested each account’s classification directly against the utility’s own criteria.
- Scale multiplies exposure. Seventeen separate misclassification errors across seven states point to a portfolio-wide pattern, not an isolated mistake at a single facility.
- Refunds and recurring savings are distinct categories. This engagement produced $374,326 in one-time refunds, plus more than $150,000 in new annual recurring savings identified across the portfolio, kept separate because they behave differently on a P&L.
- No operational changes were required. All refunds and savings were achieved without any change to hours of operation, equipment usage timing, or any other adjustment to plant operations.
This case study reflects findings and outcomes reported by Discovery Energy in connection with its engagement for a national steel company. Refund figures reflect one-time historical billing corrections tied to specific utility accounts; recurring savings figures reflect new ongoing annual value identified across the portfolio, and the $33,554 example reflects one documented account within that total, not the full portfolio-wide amount. Company and facility identifying information has been anonymized; utility names reflect the parties that issued the corrections. Discovery Energy’s audit was conducted independently and on a contingency basis, behind the company’s existing, separately contracted energy management provider.